What Is an X-Mod? Same Number as Your EMR, Different Name
Your broker says X-Mod, the bid form says EMR, and the renewal letter says experience mod. It's one number every time, and the bureau behind it is the part worth knowing.
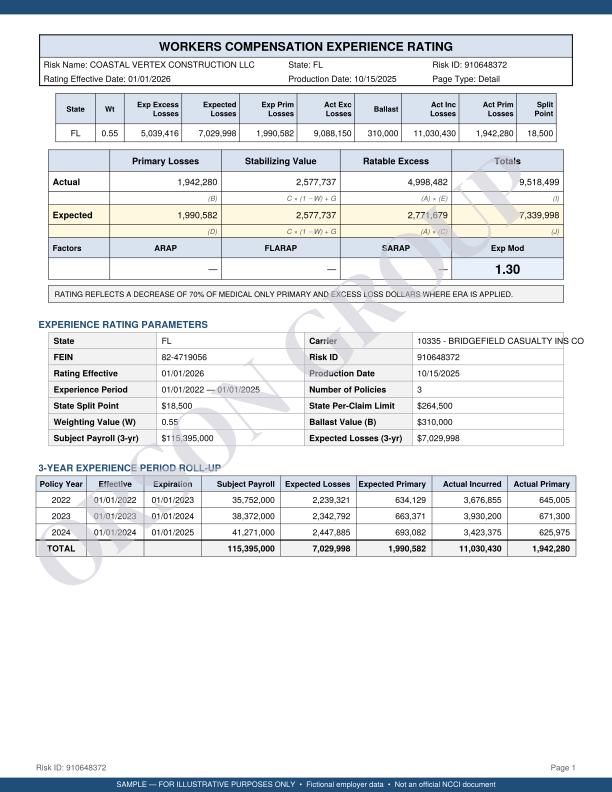
An X-Mod is the experience modification factor on a workers' compensation policy: the same number contractors call the EMR, e-mod or the mod. California's rating bureau, the WCIRB, publishes it under the X-Mod name. It compares an employer's actual losses with expected losses for its payroll and classifications. A 1.00 is average; above 1.00 raises premium, below 1.00 lowers it.
Ask three people about the same number and you can get three names for it. A broker asks for your X-Mod. The general contractor's prequalification form wants your EMR. The carrier's renewal letter calls it your experience modification, and the safety consultant says e-mod.
It's one number. So what is an X-Mod? It's the experience modification factor that multiplies every dollar of your workers' comp premium, under the name California's rating bureau uses. If someone asks for your X-Mod and you only know your EMR, you already have the answer.
Where X-Mod, EMR and e-mod come from
The formal name belongs to NCCI (the National Council on Compensation Insurance), which calculates the factor in most states. Its employer guide calls it the experience rating modification factor, shortens that to the mod, and labels a mod below 1.00 a credit mod and one above 1.00 a debit mod. A 1.00 is what NCCI calls unity: no credit, no debit (NCCI, ABCs of Experience Rating, 2021).
X-Mod is the California version. The Workers' Compensation Insurance Rating Bureau of California (WCIRB) calculates the factor for California employers and calls it the X-Mod throughout its own materials, down to the names of its data services, X-Mods and More and X-Mod Direct. Brokers well outside California use the term too, which is why a Georgia contractor can hear it on a renewal call. Online it's often typed xmod or x mod. Same number.
E-mod and ex-mod are the trade's shorthand for experience mod, common with carriers and brokers. EMR, short for experience modification rate, is the construction industry's name. It's the term on bid specifications and prequalification questionnaires, which is why most contractors learn it first.
None of the names changes the math. They all describe a multiplier built from roughly three years of payroll and claims and applied to premium the same way. On a $100,000 premium, a 1.25 mod makes the bill $125,000 and a 0.75 mod makes it $75,000 (NCCI, ABCs of Experience Rating, 2021). The guide to how the experience modification rate is built walks through the formula behind it.
Why a California X-Mod is its own calculation
The label is loose. The bureau behind the number isn't, and that's the part worth knowing.
NCCI's experience rating plan doesn't apply in California, Delaware, Michigan, New Jersey or Pennsylvania, and the four monopolistic states (North Dakota, Ohio, Washington and Wyoming) run their own systems. Indiana, Massachusetts and North Carolina use the plan, but their own bureaus produce the intrastate mods (NCCI, ABCs of Experience Rating, 2021). In the Southeast, that puts Florida, Georgia, Alabama, South Carolina and Tennessee with NCCI, and North Carolina's intrastate mods with the North Carolina Rate Bureau.
A California X-Mod is built under California's own experience rating plan, with its own eligibility threshold and its own formula. Two mods with the same value, one from the WCIRB and one from NCCI, are not the same calculation.
That stops being trivia the day a contractor works on both sides of the line. NCCI's guide walks through an employer with payroll in Florida and in Pennsylvania, a state outside the plan: NCCI publishes a mod built from the Florida experience alone, and the Pennsylvania bureau publishes its own mod for Pennsylvania (NCCI, ABCs of Experience Rating, 2021). California works the same way. A Georgia framer that takes on California work can end up holding an NCCI mod and a WCIRB X-Mod at once, two numbers from two rulebooks, each applied to its own state's premium. The two can even sit on opposite sides of 1.00.
Why the inputs matter more than the name
Whatever a bureau calls it, the factor is arithmetic on the payroll and claim values your carrier reports, and the bureau runs its formula on what it receives. A classification code error or a reserve that never came down can inflate an X-Mod just as it inflates an EMR.
The stakes don't change with the label either. On a $250,000 manual premium, every 0.10 of mod is $25,000 a year. A claim stays in the experience period for three policy years, so an error riding in the mod can get billed more than once before it ages out.
What an audit would check
An audit checks the number behind the name. That means confirming which bureau produced each mod on file and which states it covers, reconciling claim values on the worksheet against the carrier's current records, and testing the classifications that set your expected losses. Most worksheets we review carry at least one error, whatever the paperwork calls the result.
Send us your worksheet, whether it says X-Mod, EMR or e-mod, and we'll review it for free.